Pakistan’s federal government is intensifying efforts to reform the Federal Board of Revenue (FBR), with a focus on improving tax collection, expanding the tax base, increasing transparency and reducing opportunities for corruption. Prime Minister Shehbaz Sharif has directed officials to accelerate the reform process, emphasising technology, accountability, staff training and the implementation of a faceless tax assessment system.
The reforms are significant because tax collection affects the government's ability to finance public services, infrastructure, education, healthcare and other national priorities. A more effective tax system can also help reduce pressure on businesses and individuals who already comply with their legal tax obligations.
Pakistan has long faced the challenge of collecting sufficient revenue from a broad and fairly treated tax base. The government must therefore improve compliance while ensuring that tax procedures are understandable, consistent and practical for businesses of different sizes.
The current reform effort seeks to address these challenges through administrative improvements and greater use of digital systems. Its long-term success will depend on implementation, reliable technology, fair enforcement and public confidence.
Prime Minister Directs Faster FBR Reforms
On October 19, 2026, Prime Minister Shehbaz Sharif chaired a meeting on FBR reforms in Islamabad and directed authorities to accelerate their implementation. He emphasised the importance of technology, effective training, transparency and accountability in improving the institution's capacity to address the tax.
The prime minister also called for faster implementation of a faceless system in tax collection and assessment. The objective is to make the process more transparent and reduce unnecessary direct interaction between taxpayers and individual tax officials.
The government has presented these measures as part of a broader effort to modernise tax administration and improve institutional performance.
Reform is important because an effective tax system requires more than increasing tax rates. Authorities must also identify legally taxable economic activity, process information accurately, provide clear guidance and ensure that taxpayers are treated consistently.
If these improvements are implemented effectively, the tax administration could become more predictable for individuals and businesses.
However, the results will depend on the quality of implementation. Digital systems must function reliably, officials need appropriate training, and taxpayers must be able to understand the requirements that apply to them.
Why FBR Reform Matters to Pakistan
The FBR is responsible for administering major federal taxes and customs duties. Its work directly affects government revenue, business compliance and the financial relationship between the state and taxpayers.
Government revenue helps finance public services and national development. When tax collection falls short of requirements, authorities may face difficult choices involving expenditure, borrowing and other sources of financing.
A broader and more effective tax system can improve the government's ability to meet its financial obligations.
However, tax reform must also consider fairness. If the burden falls disproportionately on businesses and individuals who already comply with the law, it can discourage formal economic activity and weaken confidence in the system.
A stronger approach involves improving compliance across all legally liable sectors while making the process simpler for honest taxpayers.
This means identifying gaps in tax registration, improving the accuracy of records, reducing unnecessary administrative barriers and applying the law consistently.
For businesses, clear procedures can reduce uncertainty and make it easier to plan investments and manage operating expenses.
For the government, better administration can support more reliable revenue collection without relying exclusively on higher tax rates.
Understanding the Tax Gap
The tax gap refers broadly to the difference between the tax legally due and the amount actually collected.
It can arise for several reasons, including failure to register when legally required, underreporting of taxable income, incorrect declarations, non-payment of assessed liabilities and weaknesses in enforcement.
Some gaps also result from administrative difficulties or misunderstandings about compliance requirements.
Addressing these problems requires reliable information and a system capable of identifying discrepancies fairly.
Digital records can help authorities compare information from different sources and identify cases that require further review. Better recordkeeping can also help taxpayers correct mistakes before they develop into larger disputes.
However, a discrepancy in financial information does not automatically establish wrongdoing. Differences may result from reporting periods, legitimate deductions, incomplete records or other explanations.
For that reason, effective tax administration requires appropriate verification, clear communication and opportunities for taxpayers to respond.
A fair system should distinguish between deliberate evasion, genuine errors and cases in which taxpayers need assistance understanding their obligations.
Improving this distinction can help the FBR direct enforcement resources more effectively while protecting the rights of compliant taxpayers.
Faceless Tax Assessment: A Major Administrative Change
One of the key elements of Pakistan's tax reform programme is the introduction of a faceless system for tax audits and assessments.
The FBR established the National Faceless Centre in Islamabad in September 2026. Under the announced framework, cases are selected through a computerised, risk-based process and assigned automatically to officers. Separate officers handle auditing, assessment and quality review, reducing direct contact between taxpayers and the officials responsible for their cases.The purpose of this arrangement is to make tax administration more transparent and reduce opportunities for inappropriate influence.
In traditional systems, taxpayers may need to communicate directly with officials about documentation, assessments and compliance questions. Although direct communication can sometimes help resolve issues, excessive discretion and unclear procedures can create opportunities for inconsistent treatment.
A properly implemented faceless system can establish more standardised processes and create clearer records of decisions.
Computerised case assignment may also reduce the risk of individuals influencing which official handles a particular case.
However, technology alone cannot eliminate every problem. Digital systems must have effective security, accurate data, reliable audit trails and appropriate oversight.
Taxpayers must also have a clear way to submit documents, request clarification and challenge decisions through the applicable legal procedures.
The effectiveness of the National Faceless Centre will therefore depend on both its technical design and the quality of the administrative safeguards surrounding it.
How Digital Technology Can Improve Tax Collection
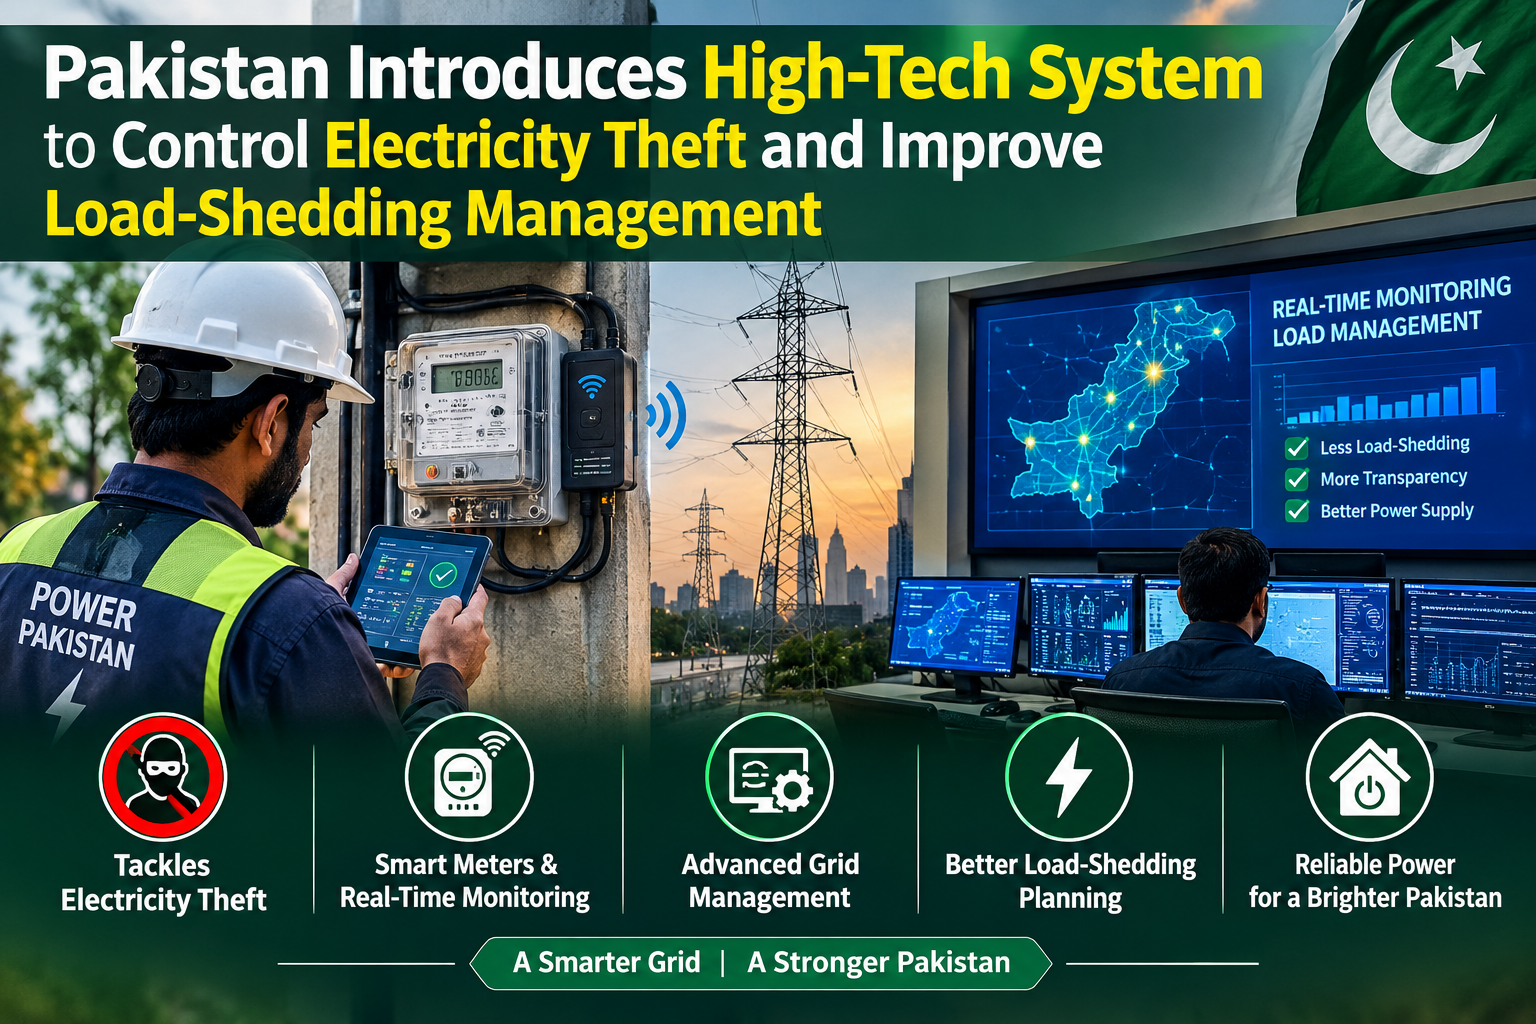
Digitalisation is becoming increasingly important in tax administration because it can improve recordkeeping, reduce paperwork and help authorities process information more efficiently.
A modern tax system may use electronic filing, digital invoicing, computerised case allocation and automated checks to identify inconsistencies in declarations.
These tools can help reduce manual processing and improve the availability of information needed for tax assessments.
For businesses, well-designed digital systems can make it easier to maintain records, submit returns and track compliance requirements.
For tax authorities, electronic records can help identify patterns that require further examination and reduce dependence on paper-based procedures.
However, the benefits depend on accessibility and reliability. Small businesses may need training, technical assistance and sufficient time to adjust to new requirements.
Poorly designed software, unclear instructions or unreliable systems can create unnecessary difficulties for businesses that are trying to comply.
The government must therefore ensure that digital reform includes practical support, not merely new technical requirements.
A successful system should make compliance easier for honest taxpayers while improving the authorities' ability to identify and address genuine violations.
Challenges Facing Businesses Under Digital Tax Reform
Pakistan's business community has broadly recognised the importance of modernising tax administration, but businesses have also raised concerns about implementation.
On October 20, 2026, representatives of the Korangi Association of Trade and Industry discussed difficulties involving digital invoicing, complicated regulations and the tax burden on compliant businesses with FBR Chairman Rashid Mahmood Langrial. The chairman said the FBR would hold further discussions with major exporters to review their concerns and identify possible solutions.
These concerns illustrate an important distinction between the goals of reform and the practical experience of businesses implementing it.
Digital invoicing can improve transaction records and help authorities identify unreported activity. However, businesses need clear instructions about registration, reporting, software requirements and the handling of technical errors.
Small companies may not have dedicated accounting teams or advanced computer systems. Additional administrative requirements can therefore create disproportionate difficulties if adequate support is unavailable.
The government must balance the objective of greater transparency with the need to keep compliance practical.
Useful measures include clear guidance, accessible support services, appropriate implementation periods and effective procedures for correcting genuine errors.
Businesses also need predictable regulations. Frequent changes or unclear requirements can make it difficult to estimate compliance costs and plan future investment.
A tax system that is both transparent and practical is more likely to encourage long-term compliance.
Broadening the Tax Base
One of Pakistan's central tax policy challenges is ensuring that everyone legally required to contribute to federal revenue fulfils their obligations.
Broadening the tax base means improving compliance across eligible individuals and businesses rather than repeatedly increasing the burden on those already registered and paying taxes.
A broader base can improve fairness by reducing the imbalance between compliant taxpayers and those who remain outside the system despite having legal obligations.
It can also help the government collect revenue more consistently.
However, broadening the tax base requires careful implementation. Not every person who has a financial transaction or appears in a database necessarily owes additional tax. Tax liability depends on the relevant law and the circumstances of the individual or business.
Authorities must therefore use accurate information and appropriate verification before taking enforcement action.
Clear rules, accessible registration procedures and reliable guidance can help people understand whether they need to register, file a return or pay tax.
The objective should be a system in which compliance becomes more straightforward and evasion becomes more difficult.
Supporting Exporters and Industrial Growth
Exporters play an important role in Pakistan's economy because international sales can generate foreign exchange, support employment and help domestic businesses expand into larger markets.
The FBR has encouraged exporters to increase the international presence of Pakistani products. At the same time, industry representatives have called for simpler regulations and assistance with digital invoicing and related compliance requirements.
These discussions highlight the need to align tax administration with the country's broader economic objectives.
Exporting businesses must manage production costs, quality standards, shipping arrangements, international competition and payment risks. Complicated administrative requirements can add further costs and uncertainty.
A well-designed tax system should support lawful trade while ensuring that businesses comply with applicable tax and customs rules.
Simplified procedures, reliable digital services and timely resolution of compliance issues can help exporters devote more resources to production and market development.
The government must also ensure that efforts to support exports do not create unfair advantages or undermine legitimate revenue collection.
The long-term objective should be to improve the competitiveness of Pakistani businesses through better administration, predictable rules and productive investment.
Transparency, Accountability and Public Trust
Public trust is an important foundation of an effective tax system.
People are more likely to view tax compliance positively when procedures are understandable, decisions are consistent and public institutions are accountable.
Transparency requires more than publishing new rules. Taxpayers must be able to understand how decisions are made, what information is required and how to challenge an assessment they believe is incorrect.
Accountability also means that officials must follow established procedures and face appropriate consequences when misconduct is established through due process.
The government's emphasis on transparency and accountability reflects the importance of these principles in the current reform programme.
Technology may help strengthen accountability by creating records of case assignments, assessments and reviews. These records can make it easier for authorised oversight bodies to examine whether procedures have been followed.
Nevertheless, digital systems require effective supervision. Automated processes must be tested, errors must be corrected and sensitive financial information must be protected.
Public confidence will depend on whether taxpayers experience meaningful improvements in fairness, clarity and service quality.
When people believe that the system operates consistently, compliance can become easier to sustain over time.
Training and Capacity Building for FBR Officials
Tax reform requires skilled staff who understand both tax law and the technology used to administer it.
The prime minister has emphasised the need for effective training as part of the wider effort to strengthen the FBR.
Training can help officials apply regulations consistently, assess financial records accurately and communicate requirements clearly to taxpayers.
As the tax system becomes more digital, staff also need skills in data analysis, cybersecurity, electronic records and the operation of computerised assessment systems.
Professional development should include practical exercises and regular updates when rules or systems change.
Officials must also understand the importance of confidentiality and responsible handling of taxpayer information.
A technically advanced system cannot deliver its intended benefits if staff lack the knowledge needed to operate it correctly.
The government can strengthen institutional performance by combining modern technology with professional training, clear performance standards and effective oversight.
Protecting Taxpayer Data and Digital Records
The expansion of digital tax administration makes information security increasingly important.
Tax authorities may handle sensitive information relating to income, business transactions, assets and financial obligations. Such information must be protected against unauthorised access, misuse and accidental disclosure.
A secure system requires appropriate access controls, reliable authentication, regular security assessments and clear rules governing how information can be used.
Data should only be accessible to authorised personnel for legitimate purposes.
The government must also ensure that digital records remain accurate and that taxpayers have appropriate procedures for correcting errors.
Cybersecurity is not simply a technical issue. A failure to protect financial information can damage public confidence and create difficulties for individuals and businesses.
Investment in secure infrastructure and staff training can help reduce these risks.
As digitalisation expands, maintaining the confidentiality, integrity and availability of taxpayer records should remain a core priority.
What FBR Reforms Mean for Ordinary Citizens
Although tax reforms may initially appear to concern government departments and large businesses, their effects can extend to ordinary citizens.
A more effective tax system can improve the government's ability to finance public services and infrastructure.
It may also help reduce the unfair concentration of tax obligations on people and businesses that already comply with the law.
However, the benefits are not automatic. Improved revenue collection must be accompanied by responsible public spending, effective administration and appropriate oversight.
For salaried individuals, shopkeepers, freelancers and other taxpayers, clear filing procedures and reliable digital services can make compliance easier.
Small businesses may particularly benefit when registration, invoicing and reporting requirements are explained clearly and technical support is readily available.
At the same time, taxpayers need confidence that their information will be protected and that disputes will be handled fairly.
The success of reform should therefore be assessed not only through revenue figures but also through improvements in service quality, fairness and public confidence.
The Road Ahead for Pakistan's Tax System
Pakistan's tax reform programme faces several important priorities.
First, the government must continue improving digital systems while ensuring that businesses and individuals can use them effectively.
Second, authorities need to broaden compliance across all legally liable sectors without placing unnecessary burdens on existing taxpayers.
Third, tax assessments must remain transparent, accurate and subject to appropriate review.
Fourth, the FBR needs trained staff, reliable technology and effective accountability mechanisms.
Finally, businesses require clear regulations and practical assistance so that compliance does not unnecessarily interfere with productive activity.
These priorities are interconnected. Better technology can improve recordkeeping, but accurate records require effective processes. Strong enforcement can improve compliance, but fair treatment is necessary to maintain public confidence.
Progress will therefore depend on coordinated implementation rather than a single announcement or administrative change.
If reforms produce a more predictable and accessible tax system, they may help support investment, improve revenue collection and strengthen Pakistan's economic management over time.
Conclusion
Pakistan's government is accelerating FBR reforms with a focus on digitalisation, transparency, staff training and stronger accountability. Prime Minister Shehbaz Sharif has directed officials to speed up implementation, while the National Faceless Centre represents an important change in how tax audits and assessments are administered.
The reforms offer an opportunity to improve tax collection and make the system more consistent for individuals and businesses.
However, lasting success will require reliable technology, clear regulations, protection of taxpayer information and fair enforcement across all legally liable sectors.
The government must also respond to practical concerns raised by businesses, particularly those involving digital invoicing, complicated procedures and compliance costs.
Ultimately, an effective tax system should collect revenue fairly, support public services and create an environment in which businesses can operate with greater confidence.
Pakistan's progress will depend on whether these reforms translate into measurable improvements in administration, compliance and public trust.
Frequently Asked Questions (FAQs)
1. What reforms is Pakistan introducing at the FBR?
The government is focusing on digital tax administration, faceless assessments, staff training, transparency, accountability and improvements in tax compliance.
2. What is the National Faceless Centre?
It is an FBR facility established in Islamabad to administer tax audits and assessments through a computerised, risk-based system with reduced direct contact between taxpayers and individual officials.
3. Why is Pakistan trying to broaden its tax base?
Broadening the tax base can improve compliance, support government revenue and reduce the disproportionate burden on individuals and businesses that already fulfil their tax obligations.
4. How can digital tax reforms help businesses?
Well-designed digital systems can simplify recordkeeping, improve filing procedures and make assessments more transparent, provided businesses receive clear guidance and technical support.
5. When will the FBR reforms produce results?
The impact will depend on implementation, system reliability, staff training and consistent enforcement. Long-term success should be measured through improvements in compliance, transparency and taxpayer experience.