Introduction
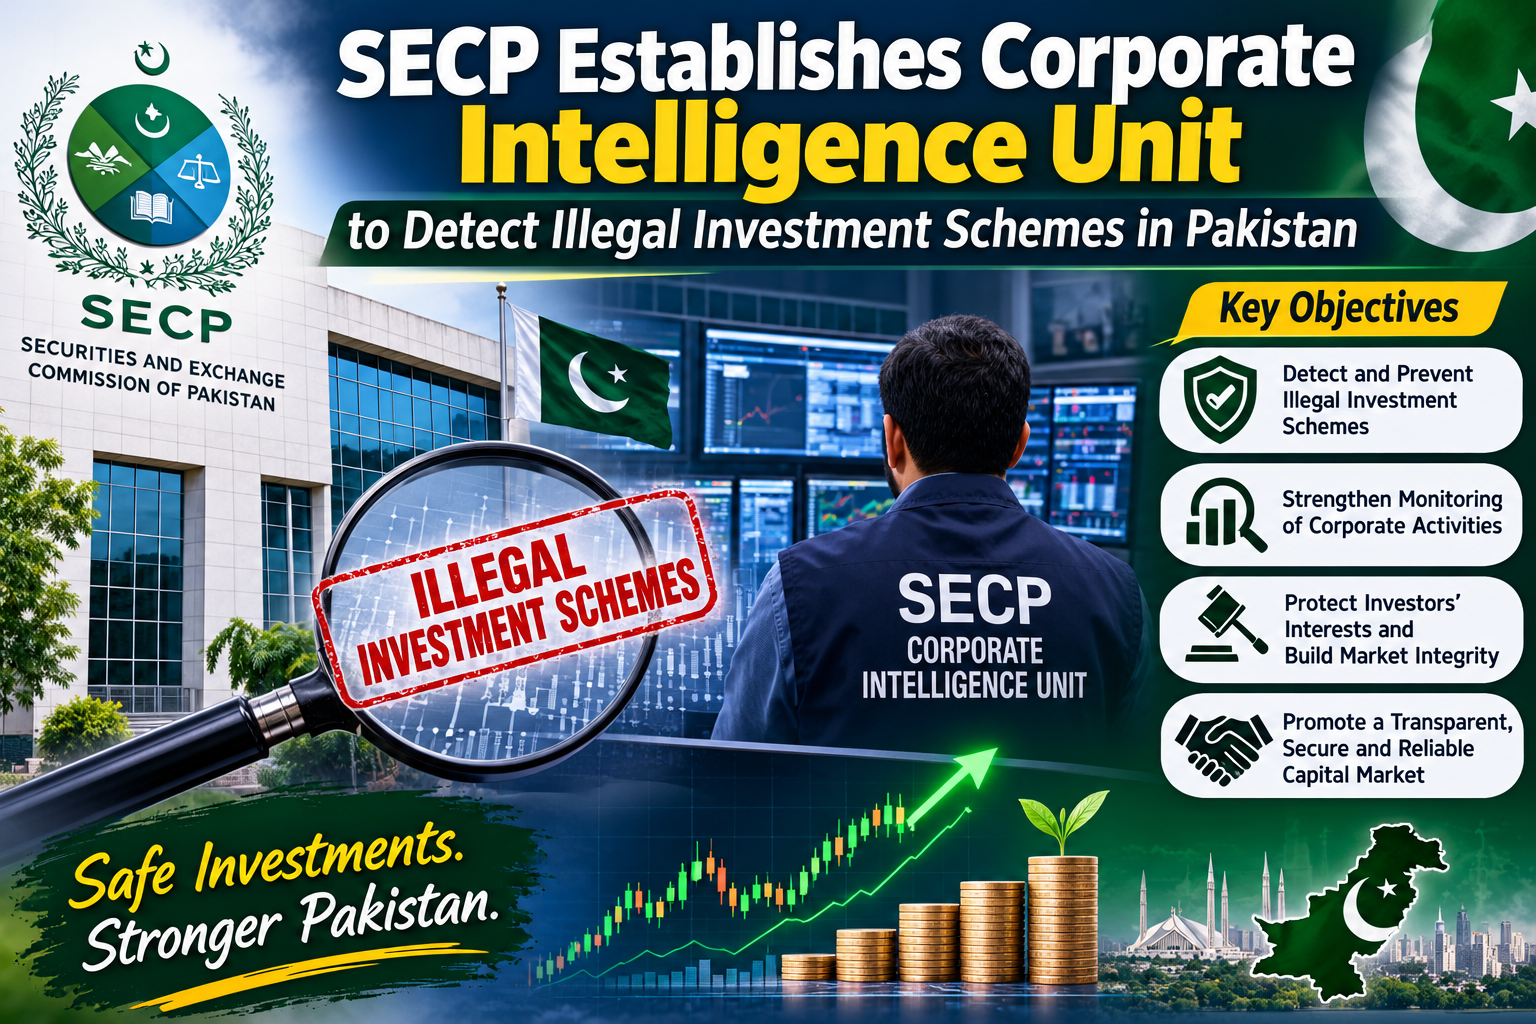
Pakistan’s Securities and Exchange Commission has taken a new step to strengthen the monitoring of suspicious financial activities by approving the establishment of a Corporate Intelligence Unit. The initiative is intended to help identify companies suspected of operating Ponzi or pyramid schemes, collecting deposits without the required licences, providing unauthorised lending services or conducting business beyond their approved objectives.
The development was reported on October 14, 2026, and reflects growing attention to the risks that fraudulent and unauthorised financial activities can create for ordinary citizens, businesses and investors.
Investment-related fraud can have serious consequences for people who spend years saving money for education, family responsibilities, business development or future financial security. When a scheme promises unusually high profits without explaining its risks, people may be tempted to trust its claims without understanding how the business actually operates.
The new Corporate Intelligence Unit is expected to strengthen the Securities and Exchange Commission of Pakistan’s ability to identify warning signs before complaints are received. According to the reported announcement, the unit will examine publicly available information, including news reports, social media activity and digital advertisements. Verified leads may then be referred to the relevant departments for investigation or enforcement action.
The initiative is important because financial activities increasingly take place through digital channels. Companies can advertise services online, communicate with potential customers through social media and promote investment opportunities to people across different cities. These developments create opportunities for legitimate businesses, but they can also make it harder for consumers to distinguish authorised financial services from suspicious offers.
The establishment of the unit does not mean that every suspicious company has committed a crime. Suspected activity requires appropriate verification and, where necessary, further investigation. Nevertheless, stronger monitoring could help authorities identify emerging risks and improve the protection of people who participate in Pakistan’s financial system.
What Is the Corporate Intelligence Unit?
The Corporate Intelligence Unit, commonly referred to as the CIU, is a specialised unit approved by the Securities and Exchange Commission of Pakistan to improve the identification of potentially unlawful corporate and financial activities.
Its primary purpose is to gather and assess information that may indicate violations of applicable laws, licensing requirements or a company’s approved business objectives.
Under the reported arrangement, the unit will monitor publicly available information and identify patterns that may require regulatory attention. Rather than waiting exclusively for individual complaints, it is intended to help the regulator recognise possible problems at an earlier stage.
This approach is significant because people do not always report suspicious investment offers immediately. Some may not realise that an activity is unlawful, while others may only become concerned after experiencing delays, receiving inconsistent explanations or discovering that a company does not possess the authorisation it claims to have.
By reviewing publicly available information, the CIU could help identify warning signs before concerns become more widespread.
The unit is being established under Section 20 of the SECP Act, 1997, as part of the chairman’s secretariat. Reports indicate that it will be headed by a director or additional director and supported by two officers.
Its effectiveness will depend on the quality of information it receives, the accuracy of its assessments and the ability of relevant departments to act on verified findings.
The unit should be understood as part of the regulator’s broader monitoring and enforcement framework, rather than as a replacement for all existing investigative procedures.
Why SECP Is Strengthening Financial Monitoring
The Securities and Exchange Commission of Pakistan regulates important parts of the country’s corporate and non-banking financial sectors. Its responsibilities include company regulation, capital market oversight and supervision of relevant financial services within its legal mandate.
A well-functioning regulatory system helps establish standards for businesses, supports transparency and provides mechanisms for addressing suspected violations.
However, financial misconduct can become difficult to detect when companies operate through complex arrangements, advertise aggressively online or present misleading claims about their services.
Some schemes may describe themselves as investment businesses, financial consultancy services, trading platforms or commercial ventures. The description alone does not establish whether an activity is authorised. The relevant question is whether the company is legally permitted to offer the particular service it is promoting.
Monitoring is therefore important because corporate registration and financial authorisation are not the same thing. A company may be registered as a legal entity without being permitted to collect public deposits, operate a particular financial service or offer every type of investment product.
The new unit could help SECP identify cases in which a company’s public claims appear inconsistent with its legal permissions or approved objectives.
Strengthening this process may also help regulators allocate their resources more effectively. When information from multiple public sources is assessed together, it may be easier to identify recurring patterns that deserve closer examination.
Understanding Ponzi Schemes
Ponzi schemes are a form of investment fraud in which money from newer participants is used to pay earlier participants, creating the appearance that an investment is generating legitimate profits.
Such arrangements may initially appear successful because some participants receive payments. However, those payments do not necessarily come from genuine business earnings.
Instead, the scheme depends on attracting additional money to meet existing obligations. If new contributions slow down or participants attempt to withdraw large amounts, the arrangement may become unable to make promised payments.
Ponzi schemes often rely on claims that an investment offers unusually reliable profits, exceptional returns or a special opportunity unavailable to the wider public. Organisers may use complicated explanations to make the arrangement appear more credible than it really is.
The essential issue is whether the claimed returns are supported by a legitimate, transparent and sustainable economic activity.
A genuine investment carries risks, and returns are not guaranteed simply because a company advertises itself professionally or claims to have a successful track record.
The SECP’s decision to strengthen early identification is relevant because suspicious arrangements may attract participants through advertising and personal recommendations before regulators receive formal complaints.
Public awareness and effective monitoring can help people recognise the importance of verifying financial claims rather than relying on promotional language.
What Are Pyramid Schemes?
Pyramid schemes are arrangements in which participants are encouraged to recruit additional people, with rewards often depending heavily on recruitment rather than the genuine sale of useful products or services.
The structure can create pressure on participants to bring in friends, relatives and other contacts. Those who join earlier may receive payments from later participants, while people who enter later may struggle to recover what they contributed.
A pyramid structure cannot expand indefinitely because the number of potential new participants is limited. As recruitment becomes more difficult, those who depend on new entrants may face losses.
Not every business that offers commissions for referrals is automatically a pyramid scheme. The actual structure, source of revenue and applicable law must be examined before reaching a conclusion.
The key concern is whether the arrangement depends primarily on recruitment and contributions from new participants rather than sustainable commercial activity.
Monitoring suspicious business models can help authorities identify arrangements that may violate applicable regulations.
Consumers should be particularly careful when a business places more emphasis on recruiting other people than on explaining what product or service is being sold, how revenue is generated and what risks participants face.
Unauthorised Deposit-Taking and Lending
The CIU is also expected to help identify companies suspected of taking deposits or providing lending services without the required authorisation.
Financial services can involve money, credit, savings and contractual obligations. Because these activities may affect the financial security of customers, the law establishes requirements governing who can provide particular services.
Unauthorised deposit-taking can expose people to significant risks. Customers may hand over money believing that a company has the legal authority and financial capacity to protect it, even when those assumptions have not been verified.
Similarly, lending arrangements can raise concerns when providers operate outside the applicable legal framework or fail to meet relevant requirements.
The regulatory status of a company must be checked in relation to the specific service it offers. Being incorporated does not automatically establish that it is authorised to collect deposits or provide regulated financial services.
The distinction matters because misleading claims about legal status can create a false sense of security.
Stronger monitoring may help SECP identify businesses whose activities appear inconsistent with their permissions. Where a matter falls within another authority’s jurisdiction, coordination may be necessary.
The overall objective is to reduce the space in which unauthorised financial activities can operate without appropriate scrutiny.
How the New Unit Will Monitor Public Information
According to reports published on October 14, the CIU will monitor publicly available information, including news reports, social media and digital advertisements.
These sources can provide useful indications of how companies describe their services, what financial claims they make and whether their public statements appear consistent with their approved activities.
For example, a company may advertise a financial product while making claims that appear inconsistent with its known authorisation. Another business may promote a service that requires a licence it does not appear to hold.
Such information would not, by itself, prove that a violation has occurred. It could, however, provide a reason for the regulator to verify the relevant facts.
The process of reviewing information is therefore an important first step rather than a final determination of wrongdoing.
The reported framework provides for verified leads to be referred to the relevant SECP departments for inquiry or enforcement action.
This distinction is important for fairness. Businesses should not be treated as guilty simply because a claim has appeared online or someone has raised a concern. Appropriate verification and procedures are necessary before regulatory conclusions are reached.
Public information can nevertheless help regulators recognise emerging patterns, prioritise potential risks and identify matters that may otherwise remain unnoticed until complaints increase.
Cooperation With Other Investigative and Regulatory Bodies
Financial misconduct does not always fall within the responsibility of a single institution. Different agencies may have different roles depending on the nature of the activity, the applicable law and the evidence available.
Reports indicate that SECP may share relevant information with agencies such as the Federal Investigation Agency, the National Cyber Crime Investigation Agency, the State Bank of Pakistan and the National Accountability Bureau where appropriate.
Such cooperation can be important when a matter involves multiple areas of concern.
For instance, a case may raise questions about corporate compliance, digital activity, banking-related issues or suspected criminal conduct. The appropriate authorities may need to assess different aspects of the same situation.
Information-sharing arrangements can help reduce unnecessary duplication and ensure that relevant leads reach the institutions with the appropriate responsibilities.
However, coordination must follow applicable legal procedures and safeguards. Information should be assessed carefully, and the role of each agency should remain clear.
Effective cooperation can also help regulators develop a better understanding of changing financial risks. Patterns identified in one area may provide useful information for assessing similar concerns elsewhere.
The CIU’s proposed role in coordinating verified leads could therefore strengthen the wider regulatory response to suspected unlawful financial activities.
Why Digital Investment Advertising Requires Attention
Digital advertising has changed how companies communicate with potential customers. Businesses can now promote their services through social media posts, short videos, online advertisements and messaging applications.
This can benefit legitimate companies by helping them reach customers more efficiently. However, it can also allow misleading financial claims to spread quickly.
An advertisement may use professional graphics, testimonials, impressive-looking figures or claims of successful past performance. None of these features independently proves that a company is authorised or that an investment is legitimate.
Some promotional messages may focus on the possibility of high profits while giving little attention to the possibility of losses. Others may create a sense of urgency by suggesting that an opportunity is available only for a limited period.
People can be vulnerable to such claims when they are under financial pressure or searching for ways to improve their income.
Regulatory monitoring of digital advertising can help identify claims that deserve closer examination. It can also support public awareness by drawing attention to the difference between advertising and independently verified information.
Consumers should understand that a polished website, large number of followers or positive online comments cannot replace proper regulatory verification.
The expansion of digital finance makes it increasingly important for public institutions to monitor risks while preserving opportunities for legitimate businesses.
How the Initiative Could Protect Investors
The establishment of the CIU is intended to improve SECP’s ability to identify potential violations before problems become more serious.
Earlier identification may allow the regulator to assess suspicious activity and determine whether further investigation or enforcement is appropriate.
This could be especially valuable where a company’s activities are attracting public attention but formal complaints have not yet been received.
However, the unit’s establishment does not mean that every suspicious arrangement will be identified immediately or that every investor will be protected from losses. Its actual impact will depend on implementation, the quality of information available and the actions taken by the relevant authorities.
Investor protection also requires cooperation from the public. People should understand the importance of checking a company’s legal status and the specific permissions associated with its financial products or services.
They should also be cautious about relying on promises of unusually high or guaranteed returns, especially when the business cannot clearly explain how those returns are generated.
A strong regulatory system combines monitoring, enforcement, transparent information and public education.
The CIU may contribute to that system by helping SECP identify potential problems earlier, while broader investor awareness can help people make more informed financial decisions.
Why Company Registration Is Not Enough
One important lesson for the public is that company registration and authorisation to provide financial services are separate matters.
Registration generally establishes that an entity has been incorporated under the relevant legal framework. It does not automatically grant permission to conduct every kind of business.
Some financial activities require specific licences, approvals or compliance with additional rules. A company may therefore be legally incorporated but still lack the authority needed for a particular financial service.
This distinction is especially important when evaluating investment offers or deposit-taking arrangements.
A certificate of incorporation should not be treated as proof that a company can lawfully accept public deposits or guarantee investment returns.
People should examine the exact service being offered and verify the relevant authorisation through the appropriate official regulatory channel.
They should also read the terms and conditions carefully and understand whether their money is being invested, lent, deposited or used in some other arrangement.
Clear public information can help reduce confusion and make it harder for misleading claims about legal status to influence decisions.
The Importance of Public Awareness
Regulatory action is important, but public awareness remains an essential part of protecting people from financial misconduct.
Many people have limited experience evaluating investment products, corporate structures or licensing requirements. They may rely on the recommendations of friends, relatives or people who appear successful online.
Personal recommendations can provide useful information, but they do not guarantee that an investment is safe or lawful.
Public education should explain basic concepts in simple language, including the difference between company registration and financial authorisation, the risks associated with unrealistic returns and the importance of reviewing written terms.
Schools, universities, community organisations and financial institutions can all contribute to improving financial literacy.
Clear public communication can also help people understand how to report suspicious activities and where to seek reliable information.
Awareness campaigns should avoid creating unnecessary panic. Not every unfamiliar business is fraudulent, and legitimate investments can carry genuine risks. The objective is to help people ask sensible questions and verify important facts before making decisions.
An informed public can support regulatory efforts by recognising warning signs and reporting concerns through appropriate channels.
Challenges the Corporate Intelligence Unit May Face
Although the new unit has a clear purpose, its effectiveness will depend on how well it handles practical challenges.
One challenge is the volume of information available online. Social media platforms and digital advertising channels generate large amounts of content, and not every questionable statement indicates a legal violation.
The unit will therefore need reliable methods for identifying relevant information and distinguishing meaningful warning signs from incomplete or misleading claims.
Another challenge is verification. Public posts may contain inaccurate information, while companies may operate through complex business arrangements. Authorities need to establish the facts before taking further action.
Coordination is also important. Some cases may require cooperation between multiple departments or agencies, and delays could reduce the effectiveness of an early-warning system.
Resources and staff capacity matter as well. A specialised unit requires appropriate training, clear responsibilities and dependable procedures to assess potential risks.
The protection of legitimate businesses is another consideration. Regulatory monitoring should be evidence-based and consistent, ensuring that companies are not unfairly penalised because of unverified allegations.
Finally, successful monitoring must lead to appropriate follow-up. Identifying a possible problem is useful only if relevant information is assessed and necessary action is taken within the applicable legal framework.
These challenges do not diminish the importance of the initiative. They highlight why careful implementation and transparent procedures are essential.
What Businesses Should Understand
The establishment of the CIU also carries a message for companies operating in Pakistan: business activities should remain consistent with applicable laws, licensing requirements and approved corporate objectives.
Companies offering financial services need to understand which permissions are required for their particular activities. They should also ensure that their advertisements accurately describe their products and do not create misleading impressions about returns, risks or regulatory status.
Clear records, transparent disclosures and effective internal compliance procedures can help businesses meet their legal obligations.
Companies should also be careful when using social media and digital advertisements to promote services. Public statements can influence customer decisions and may attract regulatory attention if they appear inconsistent with the applicable rules.
Legitimate businesses benefit from a regulatory environment in which unlawful competitors cannot easily gain an advantage by making misleading promises or avoiding legal requirements.
Consistent enforcement can help support fair competition and improve public confidence in the corporate sector.
However, the presence of a monitoring unit does not automatically establish that a particular company has violated the law. Any specific allegation should be assessed on its own evidence and circumstances.
The Wider Impact on Pakistan’s Financial Sector
A more effective system for identifying suspicious corporate and financial activities could support confidence in Pakistan’s financial sector.
People are more likely to participate in formal financial services when they understand the rules, can verify the status of providers and believe that concerns will be handled appropriately.
Businesses also benefit when customers can distinguish legitimate services from unauthorised offers.
Financial confidence can contribute to broader economic activity by supporting responsible investment, savings and access to suitable financial products.
Nevertheless, confidence depends on more than monitoring alone. Clear regulations, consistent enforcement, transparent communication and accessible complaint mechanisms are also important.
Regulators must balance the need to identify risks with the need to treat businesses fairly. Overlooking suspicious activity can expose consumers to harm, while acting on unverified claims can create unnecessary problems for legitimate companies.
The CIU’s success should therefore be evaluated through practical outcomes, including the quality of leads identified, the timeliness of referrals and the effectiveness of appropriate follow-up action.
If implemented effectively, the unit could become a useful part of Pakistan’s broader effort to strengthen corporate governance and financial consumer protection.
Conclusion
The Securities and Exchange Commission of Pakistan’s decision to establish a Corporate Intelligence Unit marks an important development in the monitoring of potentially unlawful corporate and financial activities.
The unit is intended to help identify suspected Ponzi and pyramid schemes, unauthorised deposit-taking, unlicensed lending and business activities that fall outside approved corporate objectives. By monitoring publicly available information and referring verified leads to the relevant departments, it could improve the regulator’s ability to recognise emerging risks.
The initiative is particularly relevant in an environment where financial promotions can spread quickly through digital advertising and social media. However, public information must be verified carefully, and suspected violations should be distinguished from proven wrongdoing.
Investor protection also requires public awareness. People need to understand that company registration does not automatically authorise financial services and that promises of unusually high returns should be examined carefully.
For businesses, the development reinforces the importance of regulatory compliance, accurate advertising and transparent operations.
Ultimately, the unit’s success will depend on its implementation, cooperation between institutions and the quality of follow-up action. Strong monitoring, fair enforcement and better financial literacy can work together to support a safer and more transparent financial environment in Pakistan.
Frequently Asked Questions (FAQs)
1. What is the SECP Corporate Intelligence Unit?
The Corporate Intelligence Unit is a specialised unit approved by SECP to identify potential violations involving suspicious investment schemes, unauthorised financial activities and companies operating beyond their approved objectives.
2. When was the new unit announced?
The establishment of the Corporate Intelligence Unit was reported on October 14, 2026.
3. What types of activities will the unit monitor?
It is intended to identify suspected Ponzi and pyramid schemes, unauthorised deposit-taking, unlicensed lending and other potentially unlawful corporate activities.
4. Does company registration mean a business can collect public deposits?
No. Company registration does not automatically authorise a business to collect deposits or provide regulated financial services. Specific activities may require additional licences or approvals.
5. How can people protect themselves from suspicious investment offers?
People should verify a provider’s regulatory status, understand the terms and risks, avoid relying solely on promotional claims and seek information through appropriate official channels before making financial decisions.